Add expenses to your plan
Start with what you spend today, then add the expenses you expect later.
Add your everyday spending
The simplest start is one total for everyday costs.
- Go to Plan > Expenses and select Add to Home and Living.
- Choose Living Expenses, enter what you spend in a month or a year, and select Add.
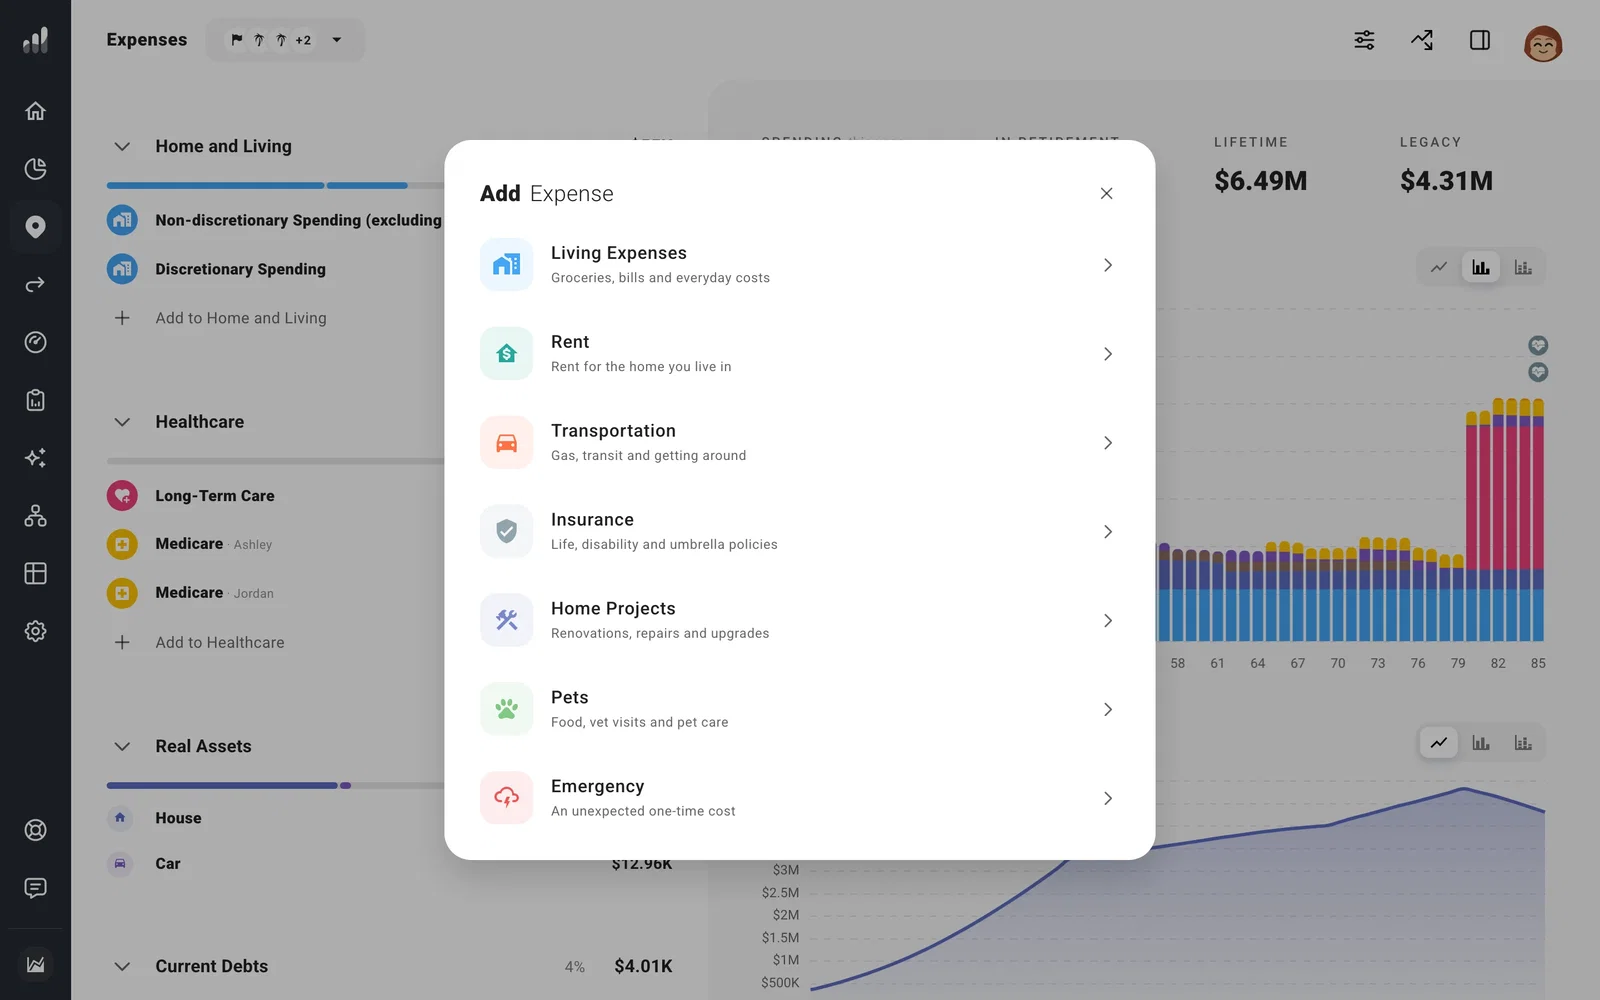
Living Expenses keeps up with inflation for the rest of your plan. If you’d rather see rent, travel, healthcare, or other spending on its own, add each one as a separate expense and take it out of your total.
Leave taxes out. ProjectionLab estimates them for you.
Add costs that come later
A wedding, a new car, college, or more travel in your first years of retirement can all go in now. When you add one, set its Time Range to a date, an age, or a milestone like Retirement.
For example, to travel more for the first ten years of retirement, add a Travel expense under Lifestyle that starts at Retirement and ends ten years later.
For a cost that comes back every few years, like replacing a car or a big family trip, turn on Recurrence and set how far apart each one is.
Costs for a child, like daycare or college, are easiest to add from the child’s page in Household, so they follow the child’s age. See Plan for a child’s costs.
Healthcare
Healthcare and medical costs grow faster than general inflation, by 2 percentage points a year by default. To change that, open Change Over Time on the expense.
In a US plan, Medicare premiums start at 65 by default. You can change your Medicare coverage and premiums. For coverage before then, see Plan for Affordable Care Act (ACA) Marketplace coverage.
Debts
Loans and credit cards you have today are added on Net Worth, and their payments show up here under Current Debts. A loan you expect to take out later, such as for a car or school, goes under Future Debts.
For a home you own or plan to buy, add the mortgage, property tax, and insurance on the home itself under Plan > Real Assets.
Essential or discretionary
Under Flexibility, mark each expense Essential, Discretionary, or a mix of both. Flexible Spending uses this to trim discretionary costs when markets fall.
Paying from a particular account
Spending comes out of your income first, then your savings. To pay one from a specific account, such as college from a 529 or medical bills from a health savings account (HSA), open Pay From and choose Specific Account. On some expenses, turn on Advanced Options under More Options to see it.
Costs taken from your paycheck
Some costs never reach your bank account, such as health insurance premiums your employer takes out of your pay. Turn on Payroll Deduction on the expense and choose the paycheck under Deduct From. Your take-home pay in the plan then matches your real paycheck more closely.
Tax-deductible costs
If an expense lowers your taxable income, turn on Tax-Deductible under Tax Handling and choose its Jurisdictions. Turn on Itemized Only for a cost that only counts when you itemize. Each year, your plan compares your itemized deductions with the standard deduction and uses whichever is larger.
In a US plan, medical expenses are handled automatically and count toward itemized deductions once they pass the income threshold, so a modest medical bill may not change your taxes.
If something looks off
An expense stops sooner than I expected
Open its Time Range and look at the end date. Until stops before that date; Through includes it.
A cost seems to be counted twice
Look for mortgage payments or property taxes entered both on the home and as separate expenses. Enter Social Security before Medicare premiums come out, since the premiums are already included in Expenses.
