Plan early withdrawals with 72(t)/SEPP
Substantially equal periodic payments (SEPP) under 72(t) can provide retirement income before age 59½ without the usual early-withdrawal penalty.
The commitment lasts at least five years or until age 59½, whichever comes later. Starting shortly before 59½ still means keeping the schedule for five years.
Set up the payments
Open the account on Net Worth, select Plan > 72t Distributions (SEPP), and choose a Method.
The RMD Method recalculates payments using the account balance and life-expectancy tables. Fixed Amortization gives a fixed payment based on the interest rate you enter. Custom Amount lets you test an annual payment you’ve already worked out.
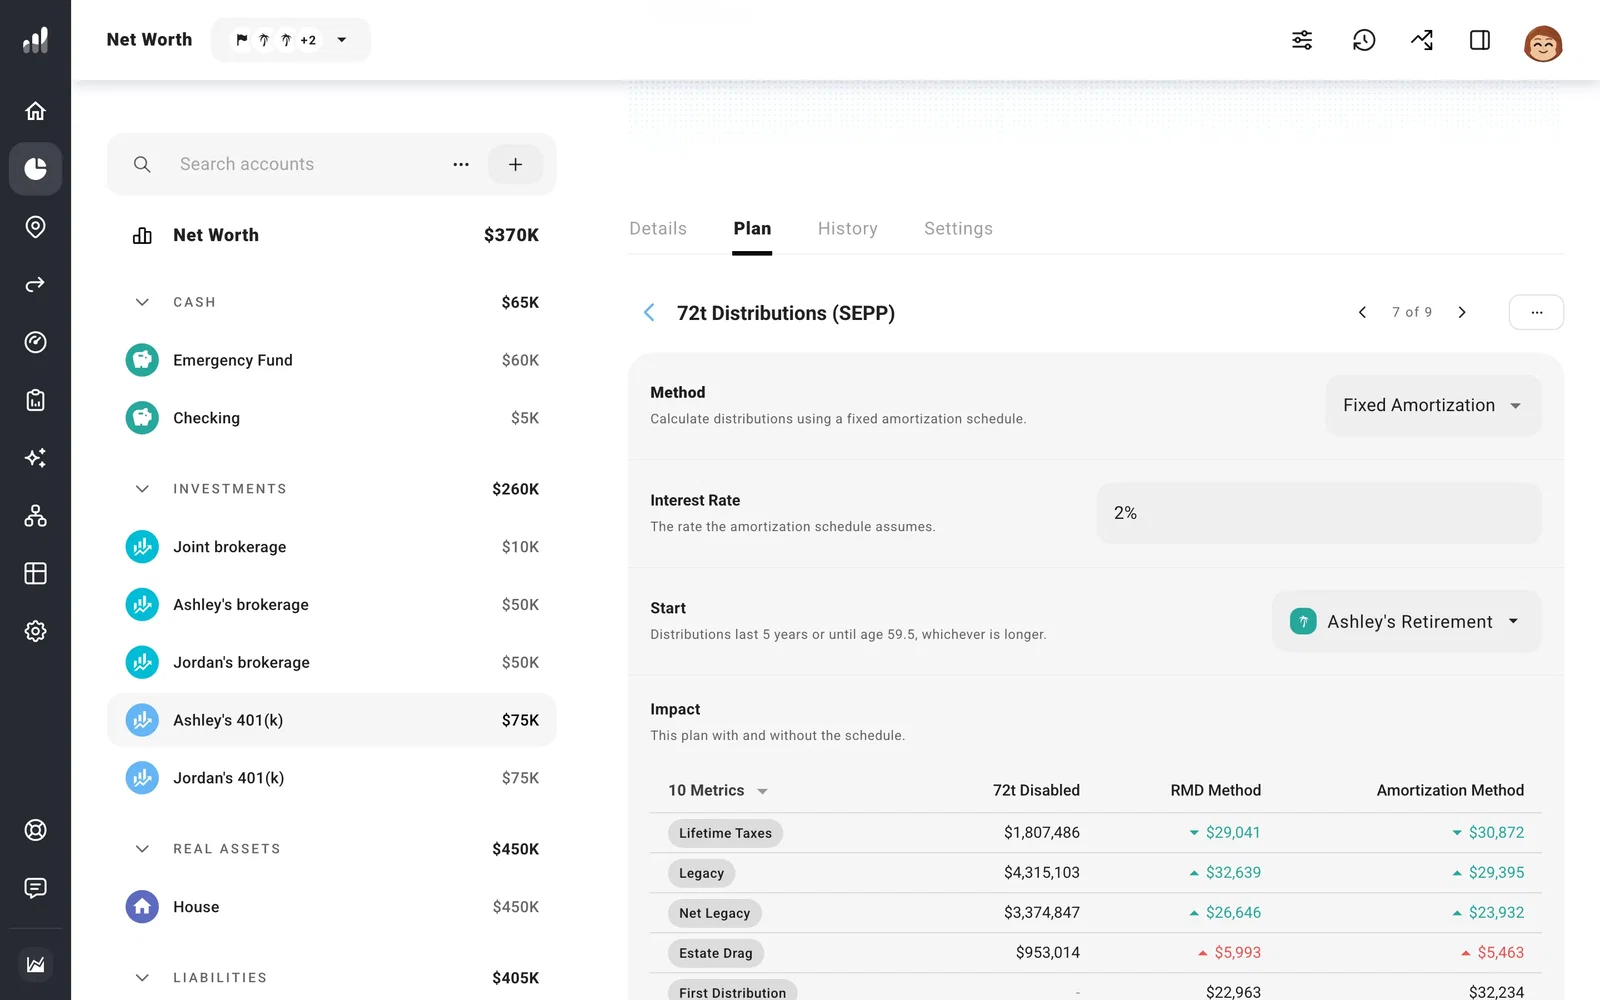
Set Start, then look at the payment amount and the comparison below the form. Compare spending, withdrawals, and taxes over the whole commitment. SEPP changes the early-withdrawal penalty; withdrawals from pre-tax savings still add to taxable income.
Other withdrawals in your plan
ProjectionLab includes retroactive early-withdrawal penalties when withdrawals in your plan break the SEPP schedule. Changing or stopping scheduled payments early, or taking an additional withdrawal, can trigger that result.
The IRS SEPP rules describe the permitted methods and interest rates.
