Why is there an early withdrawal penalty?
An early withdrawal penalty means your plan is using retirement savings before they’re penalty-free. This often appears in early retirement, when your paycheck has stopped and other savings don’t cover all your spending.
Find the account and year
Open the affected year on Plan > Overview, then open Show metrics to find withdrawals and the early-withdrawal penalty. On Optimize > Drawdown, the usage charts in Drawdown Order help you see which early withdrawals are involved.
Select that account on Net Worth. Under Settings, look at Qualified Age and Early Withdrawal Penalties. A US IRA or 401(k) uses age 60 by default: your plan counts age in whole years, and 60 is the first full year after 59½. Change it if your account’s rules differ.
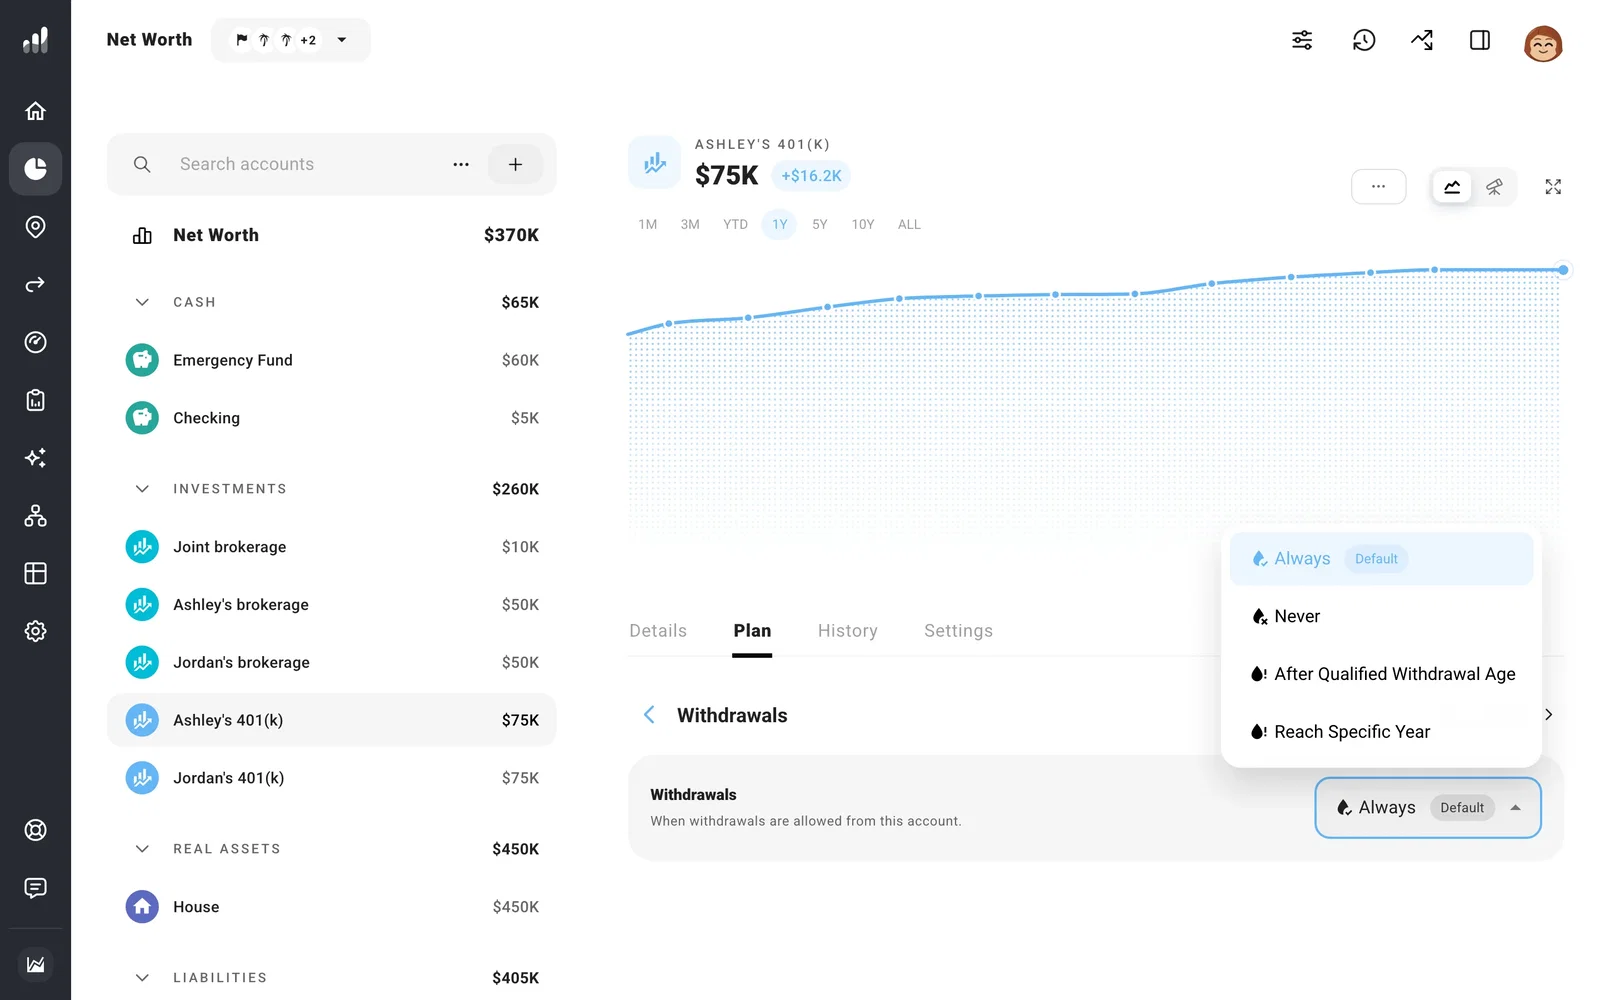
Change withdrawal timing in your plan
To have the plan wait until penalty-free withdrawals begin, choose After Qualified Withdrawal Age under the account’s Plan > Withdrawals. Check whether other accounts or income cover the gap in your forecast, then change the withdrawal order to test a different order.
You can withdraw money you contributed directly to a Roth IRA at any age without a penalty. Earnings have different withdrawal rules. Enter the contributions as Past Contributions so your plan knows how much that is.
If you’re under 59½, money converted to a Roth IRA follows a separate five-year waiting period for each conversion. ProjectionLab tracks that timing separately from your regular contributions. To plan those conversions, schedule them on the account.
If you’re modeling a 72(t) substantially equal periodic payments (SEPP) arrangement, see Plan early withdrawals with 72(t)/SEPP.
